Investing / Analysis
An office launch needs a credible occupier case
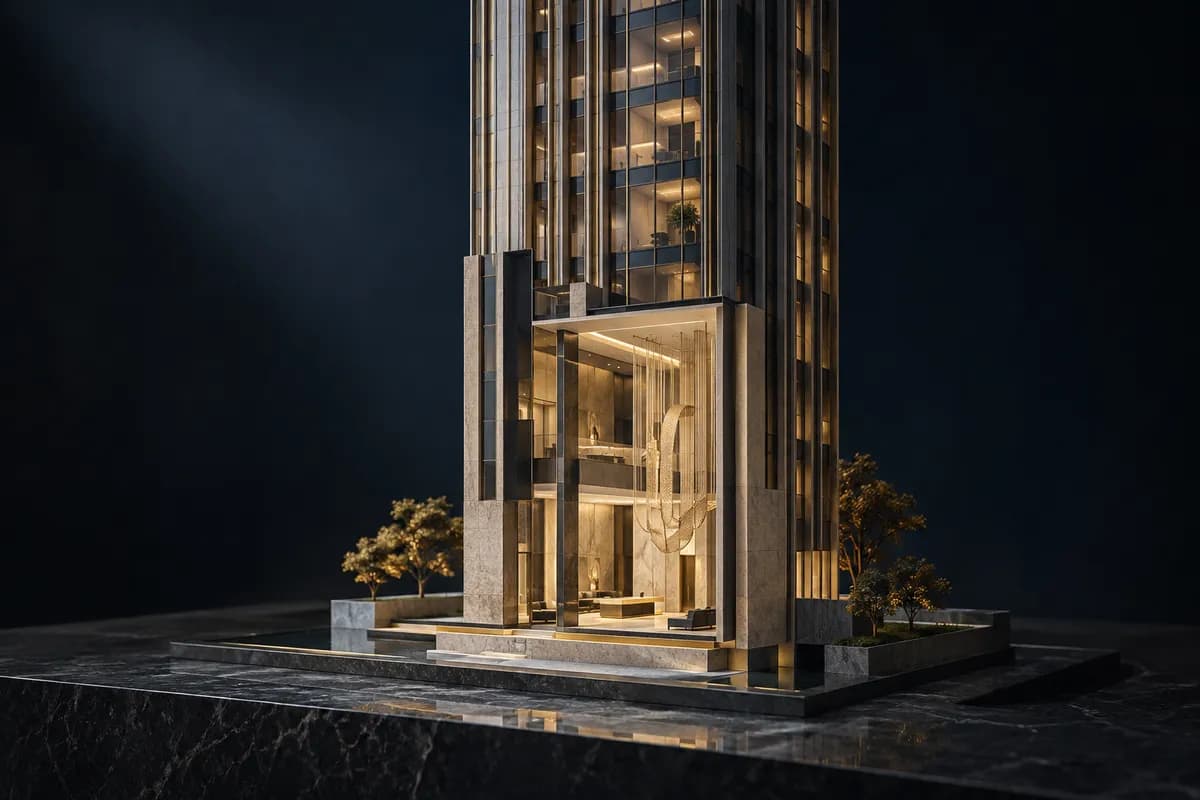
An office launch requires a credible explanation of who will use the space and why. A new building or premium description alone does not establish future leasing demand.
 THE NEWSROOM
Saved on this browser only. No account needed.
Open a story and choose “Save for later” to keep it here.
Yield watch, allocation strategy, buyer windows and investor decision support for Dubai real estate.
37–54 of 70 stories · Newest published first
An office launch requires a credible explanation of who will use the space and why. A new building or premium description alone does not establish future leasing demand.
International interest in a city does not establish the value of an individual off-plan unit. A buyer needs evidence about the product, obligations and likely use.
Citywide sales totals can provide context, but a property operates within a particular building and catchment. Local evidence is needed to connect the two.
A claim that office space is scarce needs a definition of the space being discussed. Scarcity of one specification does not establish the appropriate price of every office.
Different commercial assets require different investment cases. An office, shop and development-stage unit should not be evaluated through a single simplified return figure.
A major sporting event is not automatic evidence of property demand in another location. Commercial operators should investigate the connection rather than assume it.
Compare offices and retail premises in Dubai by business use, total cost, location and the evidence needed before a viewing or offer.
Buying a shop for occupation and buying it for rental income require different evidence. Clarify the objective before comparing candidates.
Buying and renting an office are alternatives with different commitments. Compare both against the same operating period and space requirement.
A story about overseas buyers does not establish a particular applicant's mortgage eligibility or the suitability of a unit. Financing and property evidence need separate checks.
Development cost pressure matters to a purchaser through the obligations and risks attached to the project. A general statement about a developer's resilience needs supporting evidence.
Convenience for a tenant and a return for an owner are related but distinct outcomes. An arrangement should be assessed from both sides without assuming that one benefit proves the other.
A flexible rental schedule changes the timing of payments. Its effect on an apartment's operating outcome depends on the full terms and costs.
A changing supply pipeline creates questions about timing and competition. A purchaser should distinguish proposed homes from premises that can actually be occupied.
Rent, borrowing cost and purchase price describe different parts of an ownership decision. Comparing only two of them can leave a material gap.
Overseas interest can form part of a market narrative, but it does not establish a local property's value or availability. The buyer still needs a specific case.
Tokenisation changes the structure through which an interest may be held or transferred. It does not remove the need to understand the underlying property and the holder's rights.
A long holding period gives an investment more time to operate, but it does not make the operating assumptions irrelevant. Costs and changing needs still matter.