Markets / Analysis
A commercial purchase needs an exit plan
A commercial purchase should have an exit plan as well as an entry price. That plan needs to recognise who might buy the asset and what would make it usable to them.
 THE NEWSROOM
Saved on this browser only. No account needed.
Open a story and choose “Save for later” to keep it here.
Dubai office and retail analysis for occupiers and owners: rents, supply, fit-out costs and the practical checks behind a commercial shortlist.
37–54 of 60 stories · Newest published first
A commercial purchase should have an exit plan as well as an entry price. That plan needs to recognise who might buy the asset and what would make it usable to them.
Buildings within the same office district can differ substantially. A location comparison should therefore preserve the details that matter to the occupier.
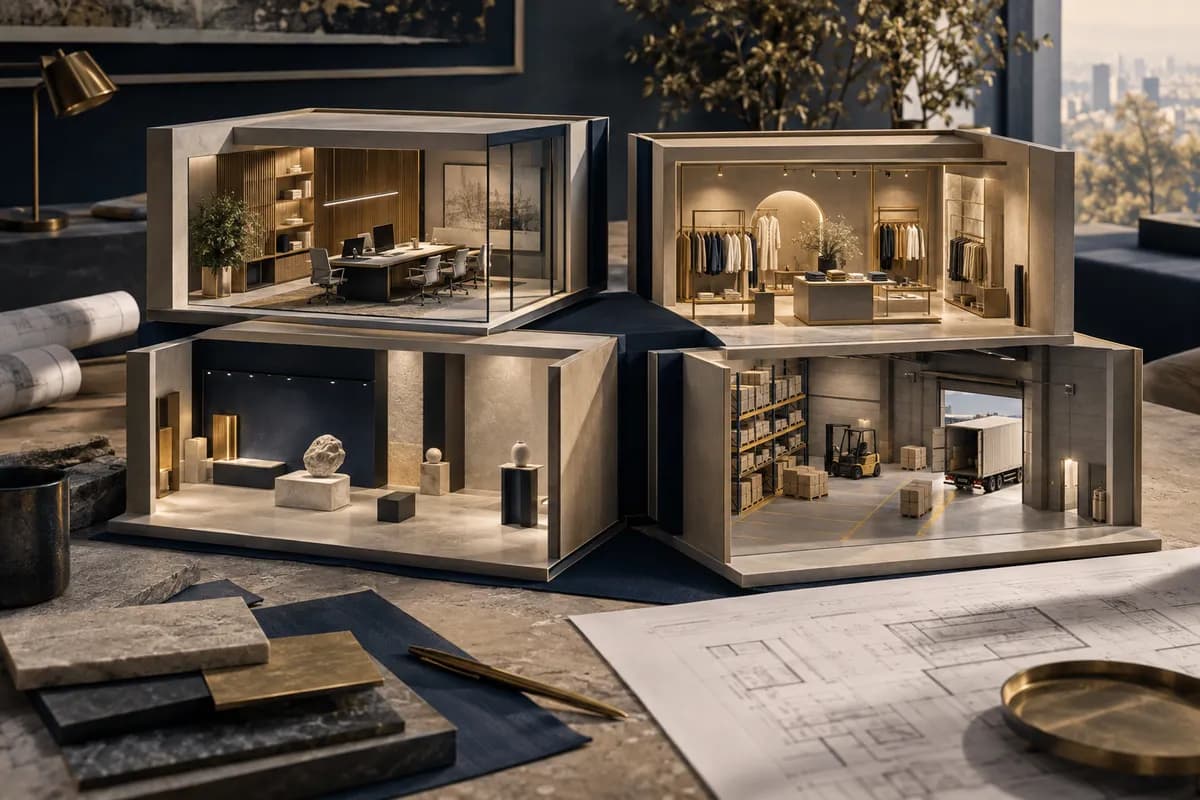
An office, showroom and warehouse solve different business problems. Comparing their rent per square foot without an operational specification can produce a misleading shortlist.
Residential and commercial leasing should be examined on their own terms. An observation about one tenant group does not establish the behaviour of another.
Prime is a marketing description unless the features behind it are defined. An office should earn its place on a shortlist through the way it serves the occupier.
Retail beneath a future residential community depends on more than the number of planned homes. A purchaser needs to understand how the intended business would reach and serve customers.
A location brief for an operator should connect the area to the work being done. Different requirements can lead to different premises even within the same budget.
A retail lease should be assessed from the customer's approach to the unit and the operator's work behind the counter. Both affect whether the premises are usable.
Buying an office can serve a long-term operating plan, but ownership also commits capital and creates responsibilities. Compare it with renting under the same business assumptions.
Office space should support the next stage of a business without depending on a single optimistic growth forecast. Layout flexibility and contract obligations need to be considered together.
An office and a community shop can suit different investment objectives. Comparing them requires separate operating assumptions before any headline yield is considered.
A flexible office layout and a flexible lease are different things. Both should be tested against the business's likely changes.
A shop's proposed rent needs to be examined alongside the costs of ownership and the tenant's ability to use the premises. An advertised yield is not an operating account.
An office launch requires a credible explanation of who will use the space and why. A new building or premium description alone does not establish future leasing demand.
Event-season retail can create unusual operating peaks. A lease still needs to work outside those peaks and within the premises' actual constraints.
A claim that office space is scarce needs a definition of the space being discussed. Scarcity of one specification does not establish the appropriate price of every office.
Different commercial assets require different investment cases. An office, shop and development-stage unit should not be evaluated through a single simplified return figure.
A major sporting event is not automatic evidence of property demand in another location. Commercial operators should investigate the connection rather than assume it.